The Offer Sitting in Your Junk Mail: How to Find Loan Deals You Already Qualify For
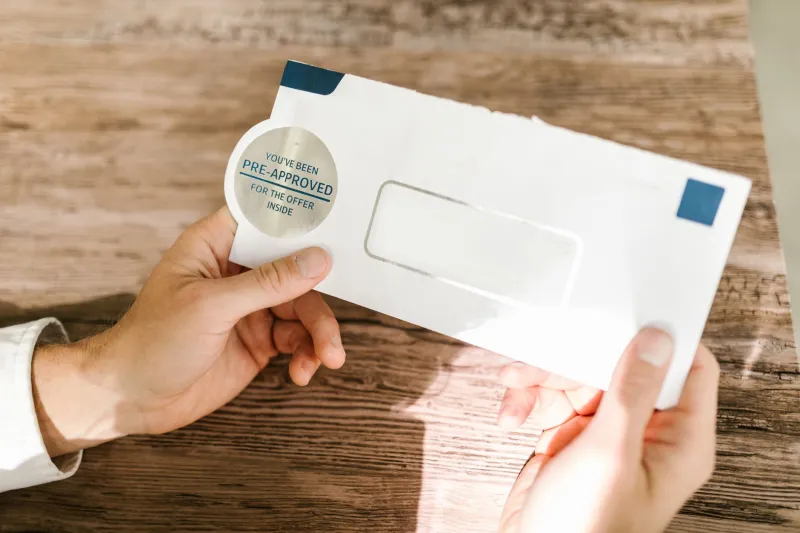
Most Americans spend weeks comparison-shopping for a loan, submitting applications, and bracing for credit pulls. Meanwhile, an envelope sits in a kitchen drawer — or an email festers unread in a promotions folder — containing an offer with better terms than anything they could find on the open market.
It sounds improbable, but it happens constantly. Lenders extend pre-qualified and pre-approved offers to borrowers based on data they already hold: deposit history, repayment records, credit bureau snapshots. These offers carry real pricing advantages precisely because the lender already knows who you are. The problem is that almost nobody claims them.
Why Pre-Screened Offers Priced Better Than the Open Market
When a lender markets to the general public, it prices for uncertainty. It must assume a wide range of risk among applicants, and the advertised rate reflects that blend. When a lender reaches out to you directly — a pre-screened credit card mailing, a pre-qualified personal loan email, an auto loan offer from your bank — the risk profile is narrower.
The economics are straightforward. Relationship lenders, particularly credit unions and regional banks, routinely extend pre-approval letters at rates a half-point to a full point below their posted rates. Some discount further for borrowers with existing accounts in good standing, payroll direct deposit, or long tenure. These discounts are rarely advertised; they are extended, quietly, to people the institution has already vetted.
Then the offers expire. Pre-approval windows commonly run 30 to 60 days. A borrower who sets the letter aside and applies three months later finds the promotion gone and the standard rate in its place.
The Four Places Your Best Offer Is Probably Hiding
A practical audit takes less than an afternoon. Work through four channels.
1. Physical mail. Look past the obvious credit card solicitations. Credit unions — including ones you may have joined years ago through an employer or community affiliation — send pre-qualified loan notices with firm rates and fixed terms. Read the fine print for phrases like "reserved rate" or "guaranteed pricing upon verification."
2. Email and online banking dashboards. Log in to every financial account you hold. Banks frequently surface pre-qualified personal loan and auto loan offers inside the portal itself, visible only after login. Search your inbox for subject lines containing "pre-qualified," "pre-approved," "your rate," or "invitation."
3. Your employer. Many mid-size and large employers offer payroll-linked lending programs, sometimes through partnerships with credit unions or fintech providers. Because repayment is deducted from your paycheck, default risk drops and so does the rate. Human resources or the employee benefits portal will list these; they are among the most underused benefits in the American workplace.
4. Existing relationships. Call your current bank and ask one direct question: "What rate can you offer me as an existing customer for a personal loan or auto refinance?" Relationship pricing is real but discretionary — it is extended to borrowers who ask.
What the Unclaimed Money Looks Like in Aggregate
Consider a representative scenario. A borrower finances $25,000 for a vehicle. The open-market rate is 8.9 percent; a pre-qualified credit union offer was 6.4 percent. Over five years, the difference is roughly $1,850 in interest. Scale that across the millions of pre-screened offers Americans receive annually and never act on, and the aggregate figure runs into the billions — money transferred from borrowers to lenders simply because nobody opened the envelope.
Reading the Fine Print Before You Claim It
A pre-qualified offer is not a guaranteed contract. Verify three things before acting:
- **Whether the rate is firm or "as low as."" Firm reserved rates are the valuable ones; "as low as" language means underwriting can move the number.
- What verification triggers. Most pre-approvals finalize only after income and identity verification, and a significant change in your credit profile can void the offer.
- Whether accepting involves a hard credit inquiry. Many pre-screened offers use soft pulls; the formal application may not. If it does, the federal rate-shopping window gives you room to compare multiple lenders within a short period with minimal score impact.
A Habit Worth Building
Once a year, open every financial letter before discarding it, click through your banking dashboards, and ask your employer what lending benefits exist. Ten minutes of administration can be worth thousands of dollars in avoided interest — the cheapest financial decision most borrowers will ever make.