Your Budget, Reimagined by an Algorithm: The New Math Behind 2025 Loan Approvals
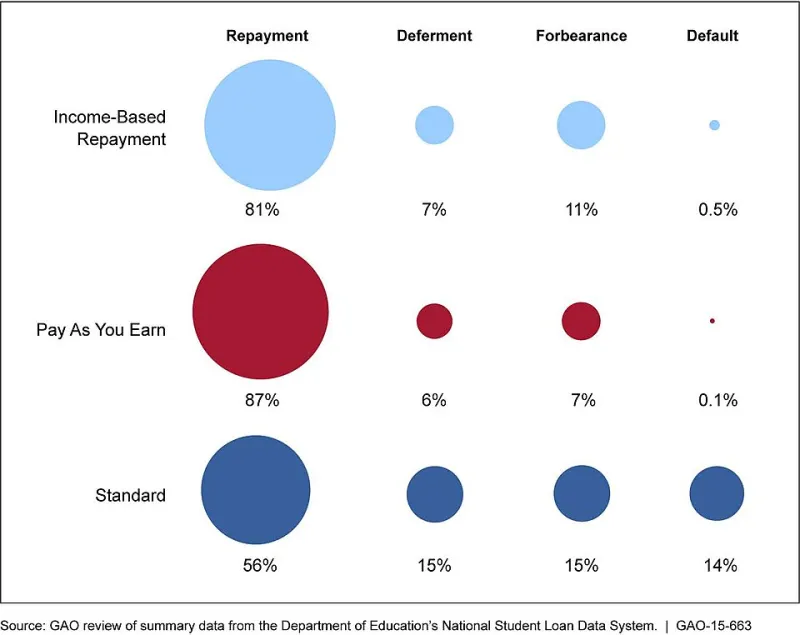
Photo: U.S. Government Accountability Office from Washington, DC, United States, Public domain, via Wikimedia Commons
For decades, American borrowers were taught one simple rule: keep your housing costs under 28% of gross income and your total debts under 36%. Lenders, the story went, lived by those same numbers. If you stayed under the line, you were approved; drift past it, and the door closed.
That story is out of date. Walk into a major lender's underwriting process in 2025 and you won't find a single gatekeeper checking your application against the 28/36 rule. You'll find a model — several of them, actually — weighing variables most consumers have never heard of. Understanding what those models see is now the difference between the rate you want and the rate you're stuck with.
Why the Old Ratio Lost Its Throne
The classic debt-to-income framework was built for a workforce that looked very different: salaried employees, single-income households, predictable monthly obligations. Today's borrower might earn half their income from ride-share driving, freelance design work, or a seasonal business — income that arrives in lumps and defies a tidy ratio.
At the same time, a growing share of household spending doesn't show up as debt at all. Streaming services, app subscriptions, buy-now-pay-later installments, and recurring deliveries don't appear on a credit report, yet they consume real income every month. A borrower who looks lean on paper may be carrying $600 in monthly commitments that no traditional ratio would ever count.
Lenders noticed. And rather than lend blindly, they built new ways of seeing.
The Variables Quietly Entering the Equation
Modern affordability assessment has expanded well beyond the two-line ratio. Several categories of data now shape outcomes:
Cash flow signals. A number of lenders and fintech platforms, with borrower permission, analyze bank transaction data to evaluate income consistency and spending patterns. A steady deposit history can offset a thinner credit file; erratic balances can undercut an otherwise strong score.
Gig income smoothing. Rather than rejecting irregular earnings outright, newer models average income over longer windows — sometimes twelve months or more — and assess its trajectory. A freelancer whose income is trending upward may fare better than the raw monthly snapshot suggests.
Subscription and obligation detection. Some underwriting approaches now account for recurring non-debt obligations when estimating disposable income. That $14.99 here and $39.99 there adds up, and sophisticated models know it.
Rent payment history. With rent being the largest expense for most American households, verified on-time rent payments have become a meaningful positive signal — one that was invisible to underwriters for generations.
None of this is secret, exactly. But it's rarely explained to borrowers, who continue optimizing for a ratio their lender may barely weigh.
What This Means at the Kitchen Table
The practical shift is this: affordability is increasingly about demonstrated stability rather than a single calculated number. Two borrowers with identical debt-to-income ratios can receive very different offers depending on how their cash flow actually behaves.
That cuts both ways. A gig worker with disciplined banking habits may now qualify where they once would have been declined. A salaried borrower with a pristine ratio but chaotic account activity — frequent overdrafts, thin reserves, heavy subscription load — may find the offer less generous than expected.
Positioning Yourself for the New Evaluation
Borrowers can adapt without gaming anything. A few steps matter more in 2025 than they did five years ago:
- Audit your recurring charges. Cancel or pause subscriptions you don't use before applying. Even modest reductions in fixed outflows improve your discretionary income profile.
- Consolidate your income into one account. Fragmented deposits across multiple banks obscure your earnings picture. A single, well-documented account tells a cleaner story.
- Document gig income early. Bank statements, 1099s, and platform earnings summaries assembled months in advance make smoothing models work in your favor.
- Report rent on time and verify it. Rent-reporting services can translate your largest monthly payment into credit-building evidence.
- Maintain a visible buffer. A consistent ending balance signals resilience. Living paycheck to paycheck with zero cushion reads as risk, regardless of your ratio.
The Ratio Isn't Dead — It's Just One Input
To be clear, debt-to-income hasn't vanished. Mortgage underwriting in particular still operates within regulatory frameworks that reference DTI, and no lender ignores it entirely. But it has been demoted from gatekeeper to one signal among many.
The borrowers who fare best under this system are those who treat their finances as lenders see them: not a ratio to be gamed, but a pattern to be demonstrated. Steady income, visible savings behavior, and lean recurring obligations now speak louder than any single percentage point.
The 28/36 rule made a generation of Americans believe affordability was arithmetic. The lesson of 2025 is that it's closer to a portrait — and you have more control over the brushstrokes than you think.