Inside the Lending Machine: How Banks Engineer Loans to Maximize Your Interest Payments
Photo: Federal Home Loan Bank Board; Kay Chernush, Public domain, via Wikimedia Commons
When you sit across the desk from a loan officer — or scroll through a lender's polished online application — the experience is designed to feel straightforward. Competitive rates. Flexible terms. Fast approval. What the brochure does not explain is that every element of a modern loan product has been carefully engineered, often with decades of behavioral research behind it, to generate the maximum possible return for the lender. For American borrowers, recognizing these mechanisms is not a matter of cynicism — it is a matter of financial survival.
The Amortization Illusion
Perhaps the most consequential and least understood feature of standard installment loans is front-loaded amortization. On a conventional mortgage or auto loan, your monthly payment remains fixed, but the portion allocated to interest versus principal shifts dramatically over time. In the early years of a 30-year mortgage, the overwhelming majority of each payment — sometimes exceeding 80 percent — goes directly to interest. Principal reduction is minimal.
Lenders benefit from this structure in a specific way: it discourages early payoff. Borrowers who refinance or sell their homes within the first five to seven years have paid a disproportionate share of total interest while retiring very little of the original balance. The loan officer who presents this structure as "stable and predictable" is not lying — but the description is carefully incomplete.
What borrowers should ask: Request a full amortization schedule before signing any installment loan. Identify the break-even point at which more than half of each payment finally goes toward principal. That number tells you the minimum holding period required to make the loan's cost structure work in your favor.
Teaser Rates and the Rate Reset Trap
Adjustable-rate mortgages (ARMs) and promotional personal loan offers frequently lead with an introductory rate that bears little resemblance to what a borrower will actually pay over time. A 5/1 ARM advertised at 5.25 percent sounds compelling when 30-year fixed rates hover above 7 percent. What the headline figure omits is the rate cap structure, the index the loan is tied to, and the margin the lender adds upon adjustment.
The Federal Reserve's rate environment of recent years has reminded millions of American homeowners that adjustable rates can move sharply and quickly. Lenders are not obligated to volunteer worst-case projections during the sales process. The Truth in Lending Act (TILA) requires disclosure of APR and certain terms, but it does not require lenders to model unfavorable rate scenarios for you.
The comparison tool available through Finance Loans US allows borrowers to input rate caps and adjustment intervals to see projected payment ranges across different rate environments — a step that every ARM applicant should take before committing.
Prepayment Penalties: The Exit Tax You Didn't Know You Agreed To
A prepayment penalty is a fee charged when a borrower pays off a loan ahead of schedule. While federal regulations prohibit prepayment penalties on most qualified mortgages originated after 2014, they remain legal and relatively common in personal loans, auto financing, and certain non-QM mortgage products.
These clauses are frequently buried in loan agreements under neutral language such as "early termination fee" or "yield maintenance provision." For a borrower who receives an inheritance, earns a bonus, or simply improves their financial position and wants to eliminate debt, a prepayment penalty can cost hundreds or even thousands of dollars — effectively punishing financial responsibility.
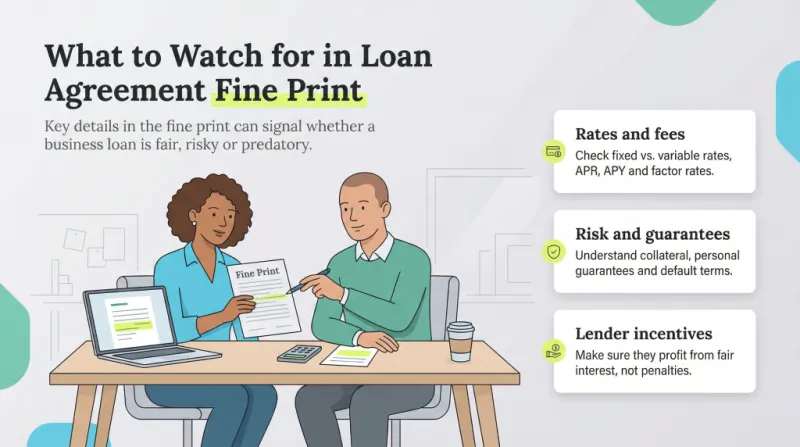
Always scan the full loan agreement for any reference to prepayment, early payoff, or termination before signing. If a penalty clause exists, negotiate its removal or factor the potential cost into your comparison of competing offers.
Minimum Payment Psychology and Revolving Credit
Credit cards and home equity lines of credit (HELOCs) operate differently from installment loans, and lenders exploit that difference through minimum payment structures. When a credit card issuer sets a minimum payment at 1 to 2 percent of the outstanding balance, the mathematical result is a repayment timeline that can stretch beyond 20 years on a modest balance — at double-digit interest rates.
The Consumer Financial Protection Bureau (CFPB) has documented the relationship between minimum payment framing and borrower behavior: when a statement displays only the minimum due, a significant share of borrowers pay exactly that amount, even when they could afford more. Lenders understand this. The minimum payment line on your statement is not a suggestion calibrated to your financial health — it is a revenue optimization tool.
A practical countermeasure is to ignore the minimum payment figure entirely and instead calculate what you would need to pay monthly to retire the balance within 12 or 18 months. Most major card issuers are now required to display this figure on statements, though it is often printed in smaller type than the minimum.
The Refinancing Cycle and Loan Churning
Refinancing, when executed strategically, is a legitimate and valuable financial tool. When executed reactively — in response to lender solicitations, rate-teaser mailers, or cash-out temptation — it can reset the amortization clock and extend a borrower's debt obligation by years.
Lenders actively market refinancing to existing customers because originating a new loan restarts the interest-heavy early years of amortization. A homeowner who refinances a 30-year mortgage after seven years does not simply continue their repayment journey — they begin a new one, potentially adding years to their total debt timeline even if their monthly payment decreases.
Before refinancing any loan, calculate the total interest cost of the new loan against the remaining interest cost of the existing one. The break-even point — where cumulative savings exceed closing costs and reset penalties — should be well within your expected holding period.
Negotiating From a Position of Knowledge
The most effective defense against lender-favoring loan structures is comparative shopping combined with specific, informed questions. When evaluating any loan offer, ask the following:
- What is the total interest paid over the full loan term?
- Is there a prepayment penalty, and under what conditions does it apply?
- How is the interest rate determined, and what index or benchmark governs adjustments?
- What fees are included in the APR versus charged separately at closing?
Lenders are accustomed to borrowers who focus exclusively on monthly payment amounts. A borrower who asks about total interest cost and prepayment terms signals financial sophistication — and often receives more competitive offers as a result.
The lending industry is not monolithic, and many credit unions, community banks, and online lenders offer genuinely transparent and borrower-friendly products. The goal is not to distrust every lender, but to approach every loan offer with the same analytical discipline that lenders apply when structuring their products. Knowledge, in this context, is not just empowering — it is measurably profitable.